Cash conversion cycle calculator
The cash conversion cycle is how many days your cash is stuck between paying for stock and getting paid for it. Enter five numbers from your books, or drag the bars: how long stock sits, how long payouts take, and how long suppliers wait. The green gap is the days your own cash pays for stock, and how much that is.
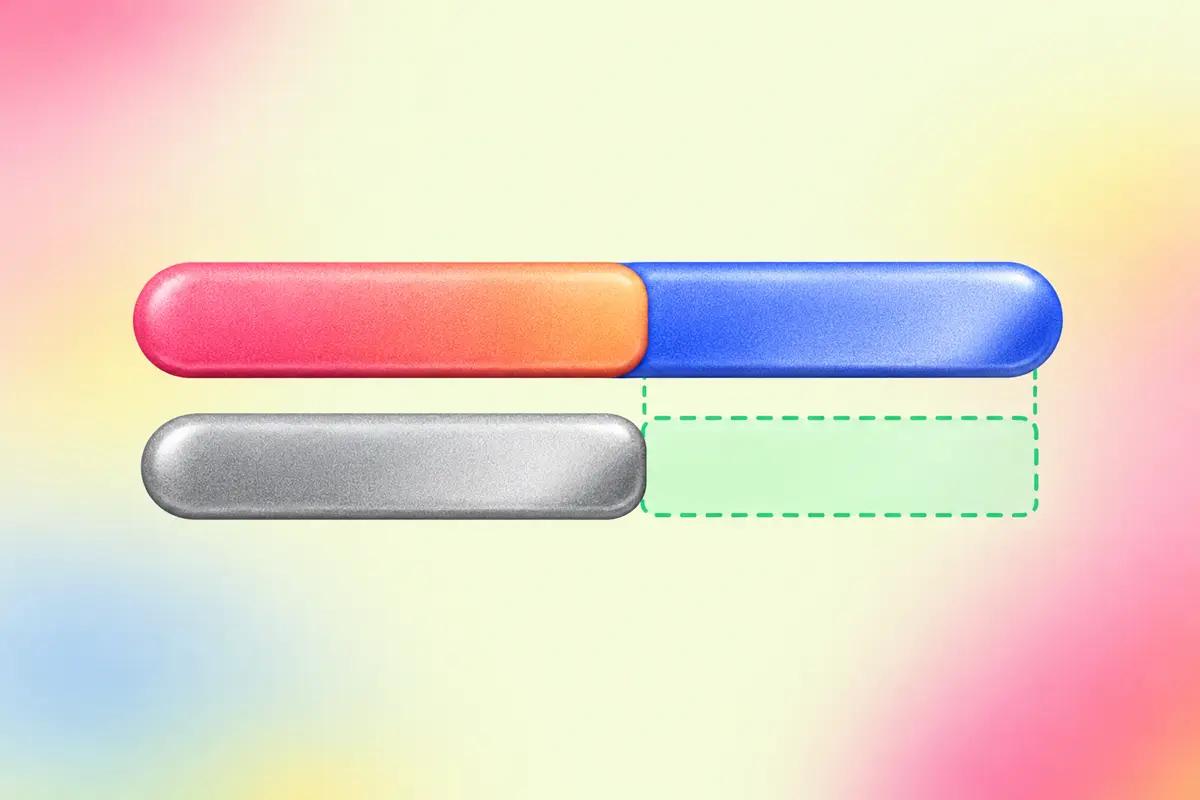
How many days is your cash stuck between paying for stock and getting paid for it? The cash conversion cycle counts them: days stock sits, plus days payouts take, minus days your suppliers wait.
Example store. Drag the ends of the bars to make it yours
Try:
A dollar paid for stock comes back in 49.9 days: stock sits 73 days, payouts take 1.2 days, and suppliers wait 24.3 days. That keeps about $85,000 of cash tied up.
- Cash tied upStock plus money owed to you, minus unpaid supplier bills: cash your store has out at any moment.
- $85,000
- Days of stock (DIO)Days inventory outstanding: stock ÷ product cost per day. How long stock sits before it sells.
- 73 days
- Days to get paid (DSO)Days sales outstanding: owed to you ÷ sales per day. How long payouts take to land.
- 1.2 days
- Days to pay suppliers (DPO)Days payable outstanding: unpaid bills ÷ product cost per day. How long suppliers wait for their money.
- 24.3 days
- Operating cycleDays of stock plus days to get paid: from stock arriving to cash in the bank, before supplier credit.
- 74.2 days
- One day less stock frees
- $1,644
- One more day of supplier credit frees
- $1,644
- One day faster payouts frees
- $4,110
- Each $1,000 more monthly sales ties up
- $680
Get a daily report card for free. Replo has a daily report card of your business ready every morning, with what changed and why.
How to read your number
The cash conversion cycle is how many days pass between paying a supplier and getting paid by a customer. On the timeline, it's the green bar from the day you pay the supplier to the day the customer's money lands. The example store holds $120,000 of stock against $600,000 a year of product cost, so stock sits 73 days. Payouts take about 1.2 days and suppliers wait 24.3, so its cycle is 49.9 days and about $85,000 of cash is tied up. A shorter cycle means growth needs less cash. Drag a bar, or type your balances in the boxes under it, and the days and dollars follow.
Why it matters
Every day in the cycle is cash you've spent and can't use yet. For the example store, one day less stock frees about $1,640, and getting 45-day terms from suppliers instead of 24 frees about $34,000. That's cash for ads or the next order, without a loan. A negative cycle, where customers pay before suppliers are due, means growth funds itself.
Every morning
Get your cash conversion cycle in a daily report
Replo reads Shopify, Meta, Google Ads and Triple Whale and has your cash conversion cycle ready every morning, with what changed since yesterday and why.

Formula
Cash conversion cycle = days of inventory (DIO) + days of sales outstanding (DSO) − days of payables (DPO)
DIO = inventory ÷ product cost for the year × 365. DSO = money owed to you ÷ sales for the year × 365. DPO = unpaid supplier bills ÷ product cost for the year × 365. For an online store, DSO is mostly the wait for card payouts, so check your payment processor's payout schedule. Cash tied up = inventory + money owed to you − unpaid supplier bills.
Other ways to calculate cash conversion cycle
- Using average balances
- DIO = ((inventory at start + inventory at end) ÷ 2) ÷ product cost for the period × days in the period
- When stock swings through the year, such as a holiday build. Averaging the opening and closing balances is how most textbooks and Corporate Finance Institute work it; use the same approach for receivables and payables.
- For one quarter or month
- DIO = inventory ÷ product cost for the quarter × 91 (or ÷ product cost for the month × 30)
- When you want a recent read instead of a year. Match the days to the period of the costs, or the answer comes out four or twelve times too big.
- DPO on purchases
- DPO = unpaid supplier bills ÷ purchases × 365, where purchases = product cost + inventory at end − inventory at start
- When stock grew or shrank a lot during the year, so what you bought differs from what you sold. Purchases is the more exact base for supplier days.
- Operating cycle
- Operating cycle = DIO + DSO
- Days from stock arriving to cash arriving, before supplier credit. It shows how long the business itself takes; the cash conversion cycle shows how much of that you fund.
- Cash tied up from days
- Cash tied up = product cost per day × (DIO − DPO) + sales per day × DSO
- When you know your days, not your balances. Drag each bar to the days you know; the calculator turns them back into balances, so the dollars match.
What is the cash conversion cycle?
The cash conversion cycle, or CCC, is the number of days a dollar spends tied up in your business: from paying a supplier for stock to getting paid by the customer who buys it.
It has three parts. Days of inventory outstanding (DIO) is how long stock sits before it sells. Days of sales outstanding (DSO) is how long you wait to be paid once it sells. Days of payables outstanding (DPO) is how long suppliers let you wait before you pay them. Add the first two and subtract the third.
How to shorten it
- Hold less stock. Order smaller, more often, and cut slow sellers. It's usually the biggest part of a store's cycle.
- Ask for longer supplier terms. Moving from paying on delivery to 30 or 60 days takes days straight off the cycle.
- Get paid sooner. Faster payouts and fewer invoiced wholesale orders cut DSO, though it's small for most online stores.
- Take preorders. Charging before stock arrives can push the cycle below zero for those products.
How to calculate cash conversion cycle: a worked example
A store sold $1,500,000 over the last 12 months, and that stock cost $600,000. Today it holds $120,000 of inventory at cost, is owed $5,000 in payouts, and owes suppliers $40,000.
- Product cost per day: $600,000 ÷ 365 = $1,643.84. Sales per day: $1,500,000 ÷ 365 = $4,109.59.
- DIO: $120,000 ÷ $1,643.84 = 73 days of stock.
- DSO: $5,000 ÷ $4,109.59 = 1.2 days until it's paid.
- DPO: $40,000 ÷ $1,643.84 = 24.3 days before it pays suppliers.
- Cash conversion cycle: 73 + 1.2 − 24.3 = 49.9 days.
- Cash tied up: $120,000 + $5,000 − $40,000 = $85,000.
The store's cash is tied up for about 50 days. Cutting stock to 60 days takes the cycle to 36.9 days and frees $21,370; getting 45-day supplier terms takes it to 29.2 days and frees $33,973.
What's a good cash conversion cycle?
Shorter is better, and below zero is best: your suppliers fund your stock. There's no single good number, because a store that sells from its own warehouse holds weeks of stock while one that makes to order holds almost none. Compare yourself with last quarter, not with another business.
What matters is the cash it ties up as you grow. For the example store, each extra $1,000 of monthly sales needs about $680 more cash in the cycle. If that's more than the profit that growth brings in, the store needs cash to grow; the profitability calculator shows when that runs out.
| Change | Cycle | Cash tied up | Cash freed |
|---|---|---|---|
| None (the example) | 49.9 days | $85,000 | |
| 60 days of stock | 36.9 days | $63,630 | $21,370 |
| 90 days of stock | 66.9 days | $112,945 | −$27,945 |
| Suppliers give 45 days | 29.2 days | $51,027 | $33,973 |
| Suppliers give 60 days | 14.2 days | $26,370 | $58,630 |
| Payouts take 3 days | 51.7 days | $92,329 | −$7,329 |
Questions about cash conversion cycle
- What is the cash conversion cycle?
- The cash conversion cycle is the number of days between paying for stock and collecting the cash from selling it: days of stock on hand, plus days to get paid, minus days your suppliers give you. A store with a 60-day cycle has its own cash tied up for 60 days on every unit.
- What is days inventory outstanding?
- Days inventory outstanding (DIO) is how many days stock sits before it sells: inventory at cost ÷ cost of goods sold × 365. $120,000 of stock on $600,000 of yearly product cost is 73 days. Fewer days means less cash tied up on the shelf.
- How do you calculate the cash conversion cycle?
- Add days of inventory to days of sales outstanding, then subtract days of payables. Each comes from a balance divided by a year of costs or sales, times 365: inventory and payables against product cost, receivables against sales. 73 + 1.2 − 24.3 = 49.9 days.
- Can the cash conversion cycle be negative?
- Yes. It's negative when customers pay you before your suppliers are due, which happens with fast-selling stock on long supplier terms, or with preorders. A negative cycle means growth brings in cash instead of using it up.
- What is a good cash conversion cycle?
- Shorter is better, and negative is best. A store that holds its own stock runs weeks; one that makes to order or drop ships runs close to zero, because it buys after the sale. Compare against your own past quarters, and watch the cash it ties up as you grow.
- How do I calculate days payable outstanding?
- Divide unpaid supplier bills by product cost for the year, then multiply by 365. $40,000 ÷ $600,000 × 365 = 24.3 days. If stock changed a lot during the year, use purchases instead of product cost for a closer number.
- What's the difference between the operating cycle and the cash conversion cycle?
- The operating cycle is days of inventory plus days of sales outstanding: how long from stock arriving to cash arriving. The cash conversion cycle subtracts days of payables, because supplier credit covers part of that wait.
Sources
Do it with Replo
Watch days of stock every week
Replo reads your store's sales and inventory, then reports days of stock by product on the schedule you set.
Prompt: “send me days of stock on hand by product every monday”